Since 2026, the market for blue-light-blocking plastic pellets—along with their upstream masterbatches and resin monomers—has shown a clear trend of divergence: while structural growth in demand has become more certain than ever, cost pressures and supply chain disruptions on the supply side are reshaping the industry’s profit distribution landscape.
On the demand side, the most enduring variable in the current global landscape is not any single short-term event, but rather the deep entrenchment of a digital lifestyle. The *2025 Remote Work Productivity Report* by RescueTime—based on tracking data from over 50,000 users—reveals that individuals working entirely remotely spend an average of 11.4 hours per day in front of a screen. This is higher than the 9.1 hours recorded for office-based workers and represents a 14% increase from the 10.0 hours observed in 2022—a significant jump from the pre-pandemic baseline of just 6–7 hours per day for typical office workers. Based on 250 working days per year, a fully remote worker experiences approximately 575 more hours of screen exposure annually than an office-based colleague. Even more concerning is the shift in when this exposure occurs: 49% of remote workers continue to use work-related devices within an hour of bedtime, and 61% keep these devices within arm’s reach while they sleep. This means that blue-light exposure is no longer confined to working hours; it has extended into the nighttime—a period when the body is most sensitive to disruptions in its sleep-wake cycle. Research from Harvard Medical School indicates that blue light suppresses melatonin for roughly twice as long as green light. The absolute increase in screen time, combined with this shift toward later-day exposure, serves as the fundamental driver behind the transition of blue-light-blocking plastic materials from "discretionary consumer goods" to "essential daily protective supplies."
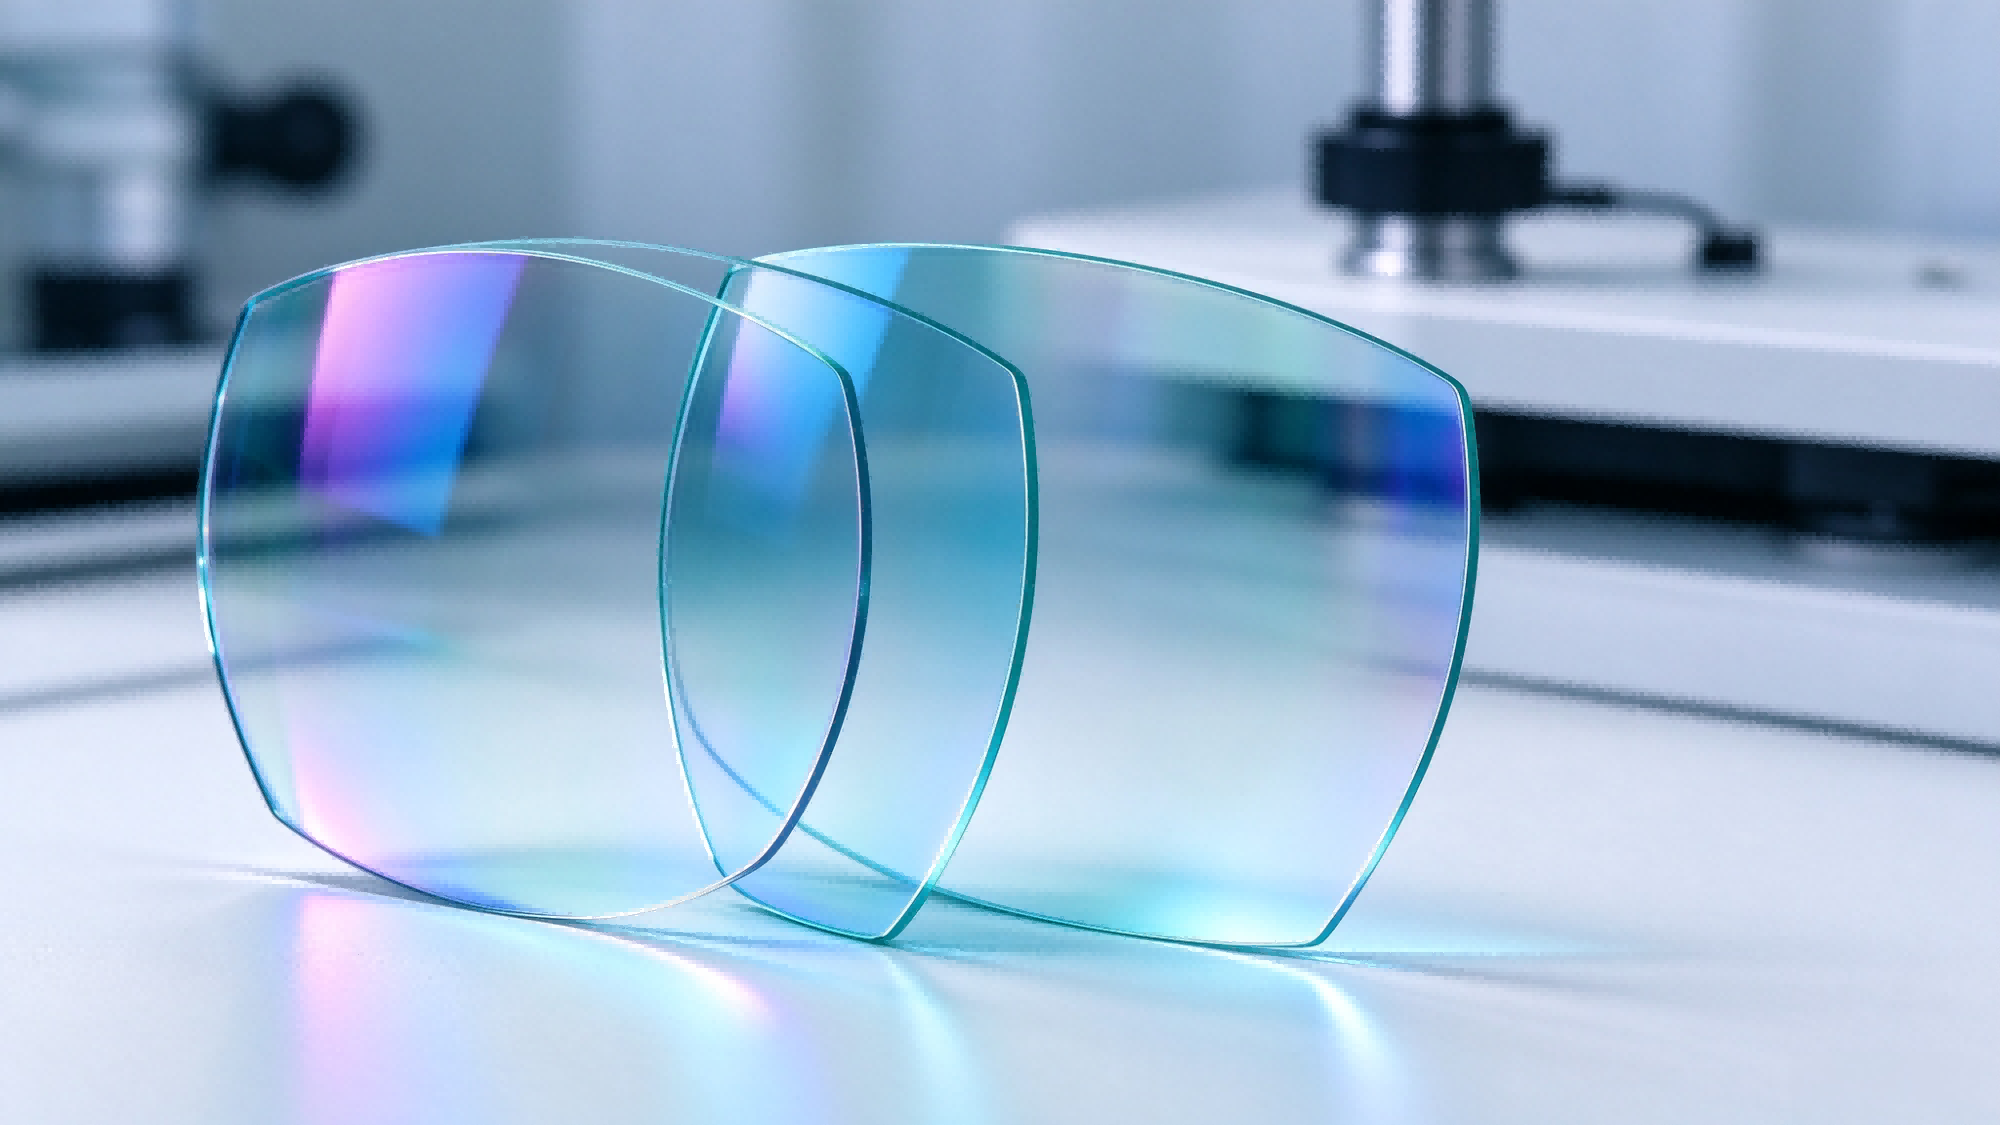
This shift in demand is directly reflected in the market size for blue-light-blocking plastic products and their upstream raw materials. Specifically, the global market for blue-light-blocking masterbatches was valued at approximately $360 million in 2025 and is projected to reach $517 million by 2032, representing a compound annual growth rate (CAGR) of 5.4% between 2026 and 2032. The downstream market for blue-light-blocking resin lenses is substantial, valued at approximately $1.981 billion in 2025 and projected to reach $3.214 billion by 2032—a compound annual growth rate (CAGR) of 7.3%. Blue-light-blocking masterbatches—based on materials such as PET, PC, or PMMA—are processed via injection molding, blow molding, or biaxial stretching into plastic components or films. These are used in applications including LED light covers, protective screens for electronic devices, and lenses. Typically incorporated at a concentration of 3%–5%, these additives target the 400–460 nm short-wave blue light spectrum while maintaining high visible light transmission. In terms of end-use, blue-light-absorbing agents are primarily integrated into PC, PET, and PMMA systems for products such as mobile phone cases, optical filter films, lenses, and coatings. In 2026, a blue-light-blocking masterbatch solution introduced by Guangtong Plastics emphasized the precise filtration of harmful blue light while overcoming the color-shift issues common in traditional materials; this reflects a growing demand from downstream clients for "functional performance without compromising color accuracy," which is driving the evolution of formulations.
However, the current global landscape exerts significant pressure on the supply side. The impact of military conflicts in the Middle East on the petrochemical supply chain is direct and clear: shortages of crude oil and chemical feedstocks have driven up the costs of base resins, while rising energy and logistics expenses have further compounded the situation—with the additives sector bearing the brunt. In May 2026, BASF announced a further price increase of up to 25% for its global portfolio of antioxidants, processing stabilizers, and light stabilizers for plastics—an additional adjustment following a previous price hike in March. The company explicitly attributed this to sharp increases in the costs of raw materials, energy, and logistics resulting from the Middle East conflicts. Since light stabilizers and processing stabilizers are essential components in blue-light-blocking masterbatch formulations, their rising costs have directly compressed profit margins for masterbatch and modified resin producers. Simultaneously, uncertainty surrounding trade policies presents an additional constraint on supply. QYResearch has identified a potential shift in the U.S. tariff framework for 2025 as a primary source of volatility for the blue-light-blocking resin lens market. The report notes that this factor is driving a restructuring of cross-border industrial footprints, capital allocation, and supply chains. The blue-light-blocking masterbatch industry faces the same variable, with global production capacity and trade flows undergoing a rebalancing process under the dual pressures of tariffs and geopolitics.
The convergence of these forces has subtly altered the competitive logic within the blue-light-blocking plastic pellet industry. On the demand side, growth is no longer driven by a single "hit" product or marketing concept; instead, it is now embedded in established lifestyle patterns—such as remote work, hybrid work, and nighttime screen usage. While growth rates are moderate (5.4% for masterbatches and 7.3% for lenses), they offer a high degree of predictability. On the supply side, companies are being tested on their resilience regarding raw material procurement diversification, cost control through formulation, and the regional distribution of production capacity. For vertically integrated firms that produce both masterbatches and downstream finished products, rising costs for upstream additives can be partially offset through formulation optimization and product mix upgrades. Conversely, small and medium-sized enterprises (SMEs) that rely solely on purchasing external masterbatches face greater pressure to pass on these costs. Looking at a longer time horizon, the conflict in the Middle East—regardless of its ultimate trajectory—has accelerated the global petrochemical industry’s focus on diversifying raw material sources. Simultaneously, adjustments to tariff frameworks are pushing the blue-light-blocking plastics supply chain to shift its priority from "cost optimization" toward "risk mitigation." In this landscape—characterized by both rigid demand and supply-side friction—companies that possess proprietary formulation technology and deep supply chain integration are best positioned to translate the industry’s structural growth into an expansion of their own market share.